


- Print Magazine
- Digital Magazine
- Newsletter

Advertisement
Features (Check It Out!)

The segment is up by 200%. It’s spiking as high as 500% in some retailers/markets. Do you know the best ways to get your share?
BY DON STUART
The last five months have seen a tsunami of change in shopper behavior and preferences. The pandemic has lifted sales of certain categories and completely submerged others. Plant-based foods have been clear beneficiaries, especially plant-based meat.
Chicago-based market research firm IRI reports that plant-based meat sales have tripled since the pandemic began, with spikes as high as 500% in some retailers/geographies. Let’s assess some of the key factors driving this growth.
The pandemic has played a critical role in this plant-based boom, compounded by closures in meat plants across the country. Resulting shortages and price increases for meat have been key in driving plant-based trial.
Among the leading brands, Impossible Foods has been on an incredible roll this summer, hitting the distribution trifecta: Natural-oriented, Mass and Grocery channels.
Trader Joe’s: “Impossible Burgers sets its sight on dominating grocery and rendering animal meat obsolete.”
Walmart: “Walmart brings meatless burger” to more than 2,000 stores across 50 states as well as to Walmart’s website and app.
Publix: Authorizes distribution in all stores.
In total, Impossible Foods’ retail distribution has grown by more than 50-fold vs. early 2020 and is now a full-scale competitor to Beyond Meat. It also just closed a $200MM funding round which will be used partly for development of plant-based pork, steak, and milk.
Beyond Meat has not been standing still, however, rolling out its own innovation, bulk packs, and lower prices. It has also issued strong quarterly results, reflecting increased focus on affordability and expanded distribution. Retail sales surged by nearly 200% vs. year-ago, helping to offset a significant decline in foodservice. Overall sales and profits exceeded analyst estimates.
Finally, Cincinnati-based Kroger and the Plant Based Foods Association (PBFA, plantbasedfoods.org), San Francisco, released results of a 12-week pilot program which indicated higher sales and trial when plant-based meat products were placed in the conventional meat section. Overall sales grew by 23%, with more significant increases in the less plant-based developed Midwest (+32%) compared to more developed regional markets. Increased sales were driven by more shoppers who purchased a wider variety of products for more occasions.
In combination, manufacturers and retailers are serving a consumer need driven by ethical, environmental, and health concerns. While some plant-based manufacturers literally want to put meat out of business, for now there’s plenty of opportunity for all.
The consumer is driven by the growing flexitarian segment. Traditionally, foods that replaced animal products have been consumed primarily by vegetarians and vegans. With new products, this is no longer true: a “flexitarian” can be described as someone who does not adhere to one specific diet style, combining meat and plant-based consumption regularly. We prefer the phrase, “will eat most anything” as a flexitarian descriptor. This is creating exceptional, incremental opportunities for plant-based products as an addition to traditional forms as noted in chart #1 and chart #2.

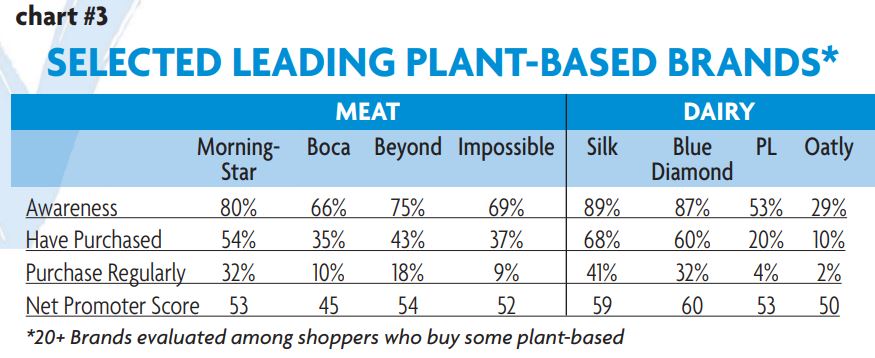
This brand assessment evaluates awareness, purchase, and net promoter score. The net promoter score is based on a 10-point scale where the bottom ratings are subtracted from the top 2 to yield a net score. The mid-tier ratings are not included in the equation. See chart #3.
Stock top brands of plant-based meat and dairy. It is not an either/or situation between traditional and plant-based products.
Be prepared to authorize new brands and items in new categories as they will provide opportunities to satisfy unmet needs.
The emergence of private label in plant-based meat will broaden and, if expectations are met, will be successful.
Pricing plays a key role: price declines among plant-based meat alternatives, along with price increases among conventional meat offerings, have further incentivized giving plant-based a try.
A few things come to mind when considering these preferences. The burger is the driver at this point, and beef-style alternatives are on track to overtake traditional veggie burger penetration. Pork, the most popular meat protein globally, lags significantly behind traditional beef-style meat alternatives.
And, if we dissect vegan/vegetarian buyers, there is higher preference for traditional veggie burgers (78%) vs. beef-style alternatives (57%). Clearly the appeal of a product that looks, tastes and chews like beef is important to traditional meat eaters and those who would “eat most anything.”
chart #3
Key Findings:
Dairy is the more mature category. The business has consolidated around two major brands, although there are up-and-comers, including Oatly. Private label is quite developed.
In plant-based dairy, other categories such as cheese and yogurt are not yet as developed.
The plant-based meat category is bifurcated into traditional plant-based meat with Boca and Morningstar as top brands, and Impossible and Beyond in the beef-like segment. The overall business has consolidated around two brands in each segment. We do not see the emergence of private label at this point in the top 20 brands, although Kroger has been a leading player in the development of plant-based private label meat alternatives.
The net promoter scores are all very competitive – generally more than 50 – which would indicate that consumers not only repeat purchase but also recommend the product.
Consumers are buying both traditional meat and plant-based meat, traditional dairy and plant-based dairy in increased quantities this year. While we do not know what the new normal will be, we anticipate increased sales growth, distribution growth, and awareness of all plant-based products, especially in the meat category. We also anticipate consolidation around top brands and the emergence of private label offerings in plant-based meat similar to what has been experienced in plant-based dairy.
Don Stuart is a managing partner at Cadent Consulting Group (cadentcg.com) with offices in Wilton, Conn., and Evanston, Ill. He can be reached at [email protected].
Advertisement

Advertisement

#1 IN AD REVENUE
TARGETED READERS
AWARD WINNING
